Celebration of Italian National Day in Atlanta

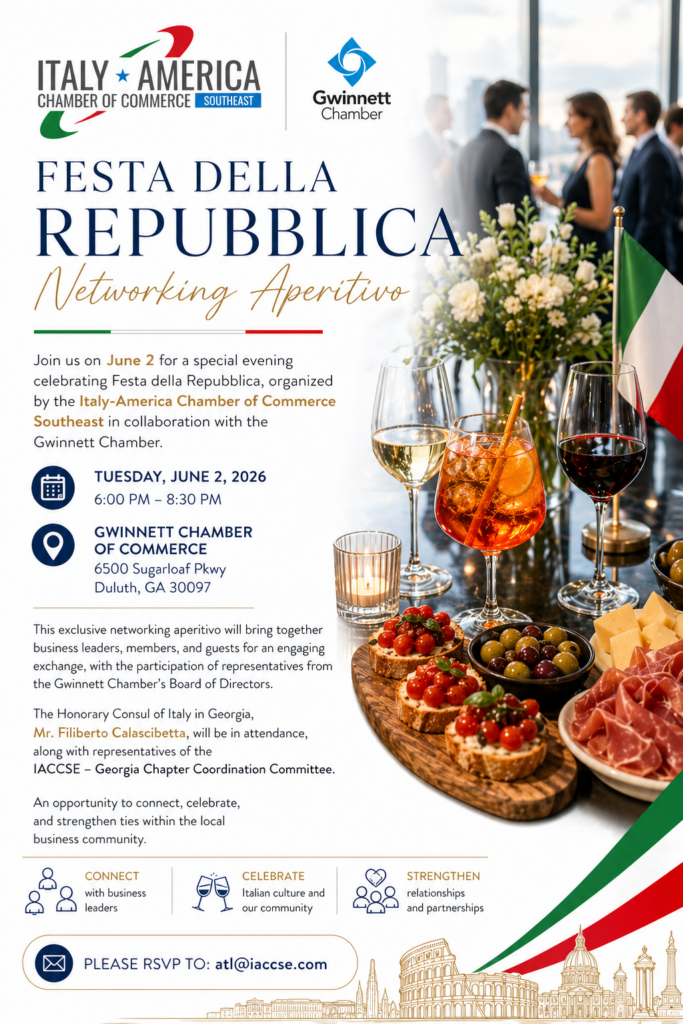
The Georgia Chapter of the Italy-America Chamber of Commerce Southeast will celebrate Italian National Day with a special networking cocktail organized in collaboration with the Gwinnett Chamber of Commerce.

The reception will bring together board members of the Gwinnett Chamber, representatives of the Coordination Committee of the IACCSE Georgia Chapter, IACCSE members, and the Honorary Consul of Italy in Georgia, Filiberto Garascibetta.

This gathering will offer a valuable opportunity for our current members to connect with prominent representatives of the Gwinnett business community, while enjoying an evening in celebration of the Italian Republic and the strong ties between Italy and Georgia.

The Chamber is also planning additional initiatives in June, including a roundtable dedicated to tariffs and duties, featuring a best-practice exchange among CEOs members of our Chamber.

Stay tuned for more details.

You can reach Ludovica Guglielmo, Project manager, for the IACCSE – Georgia Chapter at: atl@iaccse.com .

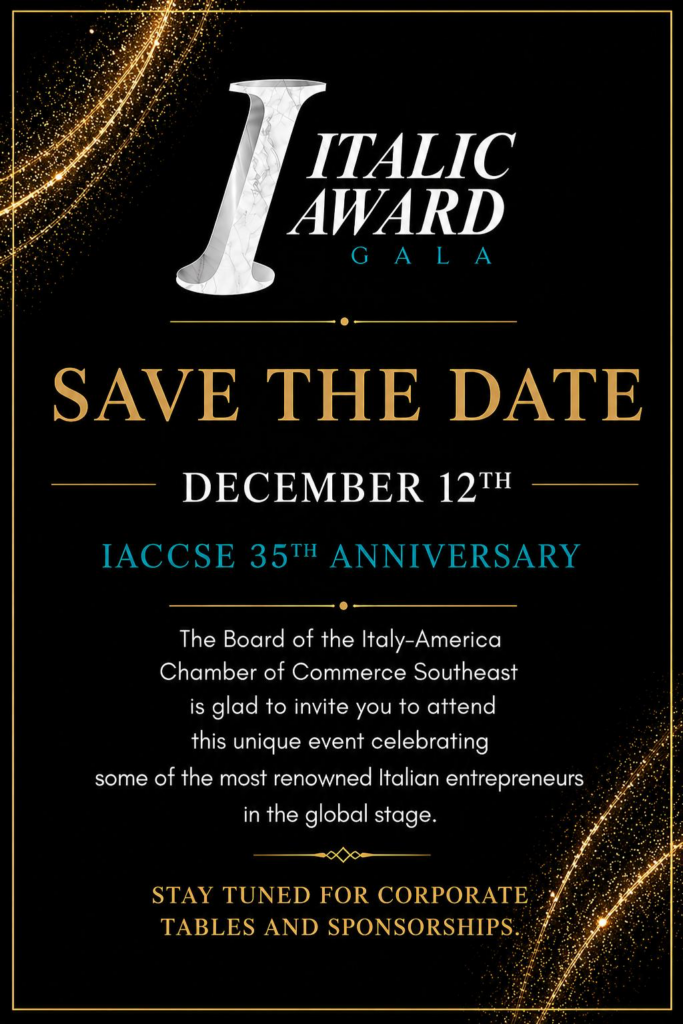
Save the Date: Italic Award Gala 2026

The Italy-America Chamber of Commerce Southeast is pleased to announce that the Italic Award Gala will take place on Saturday, December 12, 2026, at the prestigious JW Marriott Marquis in Downtown Miami.

This year’s Gala will be a truly special occasion, celebrating the 35th anniversary of the Chamber and honoring its longstanding commitment to strengthening business ties between Italy and the United States. The event will also coincide with the celebration of the G20 Summit, adding further significance to this important milestone.

The evening promises to be a spectacular event, featuring many surprises and exceptional guest speakers, including some of the most prominent Italian entrepreneurs on the global stage, soon to be revealed.

In the coming weeks, the Chamber will share additional details regarding sponsorship opportunities and corporate tables.

The Board of Directors of the Italy-America Chamber of Commerce Southeast is delighted to invite members, partners, and friends to join us for what promises to be an unforgettable evening.

IEEPA Refund Update

U.S. Customs and Border Protection (CBP) recently published a document titled “International Emergency Economic Powers Act (IEEPA) Duty Refunds” – https://www.cbp.gov/trade/programs-administration/trade-remedies/ieepa-duty-refunds – as well as CSMS # 68315804 – https://content.govdelivery.com/accounts/USDHSCBP/bulletins/4126a9c– , which summarizes the incoming refund process. 

CBP launched the Consolidated Administration and Processing of Entries (CAPE) April 20, 2026, as Phase 1 only for unliquidated entries and liquidated entries within 80 days of liquidation. 

CBP also specified the actions required for requesting refunds: 

The Importer of Record (IOR) and its customs broker must have an ACE account.  

ACH must be set up in ACE.  

The IOR or its customs broker must submit the request for refund (CAPE Declaration) via CAPE in the ACE system.  

The CAPE Declaration must be submitted as a .CSV file in ACE. 

The CAPE Declaration template will be available in the ACE system. 

Once the CAPE Declaration has been processed and validated by CBP, ACE will liquidate or reliquidate the entries by removing the IEEPA HTS codes.  

Refunds will be issued directly to the IOR’s bank account recorded in ACE or to a party the IOR has designated to receive refunds on its behalf via CBP Form.

Lastly, after the CAPE Declaration is accepted by CBP, refunds will be issued within 60 to 90 days.  

What Importers Should Do:

  • If not already created, create an ACE account immediately 
  • If you have an ACE account but you haven’t connected in the past 45 days, call ACE Support – https://www.cbp.gov/trade/automated/ace-support – immediately to reactivate your account  
  • Register to receive refunds via ACH using your U.S. bank account  
  • Prepare an ACE report covering all entries with IEEPA duties (including the liquidation dates)  

For Phase I refund requests, Prepare a CAPE Declaration consisting of a .CSV (comma-separated values) file containing only entry numbers, and only entry numbers 1) for which IEEPA duties were paid, and 2) that are unliquidated or liquidated less than 80 days prior to the date the Declaration will be submitted.    

CBP began accepting refund requests on April 20.

Tax Considerations for C-Suite Moves to the U.S.

By Mowery & Schoenfeld

Author: Ricardo Aramburo Williams, International Tax Principal

For non-U.S. executives, relocating to the United States, whether for business or personal reasons, represents a meaningful opportunity, but also significant tax complexity. From compensation structuring and asset reporting to potential exit taxes in the home jurisdiction, the scope of considerations can be substantial. Taking steps early to coordinate with experienced cross-border advisors helps manage both pre- and post-move implications effectively.

Substantial Presence Test

The first question is a matter of whether U.S. tax residency is an option. This determination is often governed by the substantial presence test, which is met if the executive is physically present in the United States for:

  • 31 days during the current tax year, and
  • 183 days during the current year and the two preceding years, calculated using a weighted formula (all days in the current year, 1/3 of days in the first preceding year, and 1/6 of days in the second preceding year).

Meeting this test generally results in U.S. tax residency, subjecting the executive to U.S. taxation on worldwide income.

In cases where an executive may be considered a tax resident in both the United States and their home country, applicable income tax treaties often provide “tiebreaker” rules. These rules assess factors such as permanent home, center of vital interests, habitual abode, and nationality to determine primary residency.

Dual residency and tiebreaker rules

Executives from countries that have income tax treaties with the U.S. can sometimes be considered residents of both nations simultaneously, known as dual residency. To address this issue, most of these treaties include “tiebreaker” rules that establish which taxing jurisdiction has primary residency status for tax purposes. These rules generally consider factors including permanent home, center of vital interests (read: where their personal and economic ties are strongest), habitual abode (read: where they actually live), and nationality. These tests can create a space for the individual to “overrule” the general substantial presence test rule.

Worldwide Taxation vs. Territorial Taxation

The U.S. follows a worldwide taxation system, in contrast to the territorial regimes common in many other jurisdictions. As a result, all residents’ income, regardless of source, is subject to U.S. federal income tax. This includes employment income, investment returns, rental income, and gains from the disposition of non-U.S. assets.

For executives transitioning from territorial systems, this shift can materially affect both tax exposure and planning strategies. The timing of income recognition, compensation structuring, and asset dispositions should be evaluated carefully in advance of relocation.

Importantly, U.S. tax compliance obligations extend beyond income. U.S. residents are required to report certain foreign financial accounts and assets annually, including interests in foreign bank accounts, investment portfolios, and other financial holdings. Non-compliance carries significant penalties, making proactive planning essential.

Reporting foreign income and assets

U.S. tax residents must report income from foreign sources, including wages, interest, dividends, capital gains, rental income, and even certain retirement plans. Reporting rules also apply to foreign bank accounts and financial assets, with a series of forms that should be completed with income tax returns. A good international tax advisor can ensure you’re not only paying the proper amount of tax (and not more), but also complying with the complex system of reporting rules, avoiding costly audits and penalties.

Taxation of executive compensation

The structure of executive compensation — salary, bonuses, stock options, deferred compensation, and benefits — can have different tax treatments depending on residency status and sourcing rules. Contact a tax professional to determine the proper sourcing prior to moving.

Salary and bonuses

When a U.S. tax resident earns a base salary and cash bonuses, the income is generally subject to U.S. tax regardless of the country where they payments were made. Compensation earned before becoming a U.S. tax resident may remain taxable in the executive’s home country. Legal and international tax professionals can help with sourcing income as part of your pre-move planning process.

Equity compensation

Stock options, restricted stock units (RSUs), and similar awards can add nuance and complexity for boundless leaders. The U.S. taxes equity compensation based on the period over which it is earned (grant, vesting, and exercise dates) and the executive’s residency during these periods. Carefully tracking grant dates, vesting schedules, and exercises will help ensure income is taxed when and where it should be.

Deferred compensation and foreign retirement plans

Deferred compensation arrangements and foreign pensions are very common in the global executive community. The U.S. tax treatments for these can differ from those in the home country, potentially triggering earlier income recognition or eliminating tax benefits. While tax treaties may offer some relief, a thorough analysis is important to help avoid unintended consequences.

State and local taxes (SALT)

The U.S. federal tax system is further complicated by state and local taxes. State residency is often based on physical presence, but specific criteria differ significantly by state. States such as California and New York are known for high taxes and aggressive enforcement, making it especially important for executives to plan ahead, either to avoid double taxation or take advantage of credits for foreign taxes paid.

Social Security and Medicare

Most U.S. tax residents are subject Social Security and Medicare taxes on earned income. Certain countries have “totalization agreements” with the U.S., which exist to help prevent duplicate contributions and align eligibility for retirements across borders. These agreements should be reviewed in detail to understand the specific benefits available to an executive under each applicable treaty. Without these agreements, global executives may end up paying into multiple programs. U.S. legal and tax professionals are key in property interpreting, understanding, and applying these treaties to maximize benefits and minimize taxes when relocating.

Exit taxes and departure planning

Moving to the U.S. may trigger exit taxes in the executive’s home country, especially for those deemed “covered expatriates” or high-net-worth individuals. Careful pre-departure planning, including realizing capital gains, accelerating deductions, and restructuring assets, can minimize tax costs.

Estate and gift tax implications

Becoming a U.S. tax resident can expose your global assets to U.S. estate and gift taxes, which can be broader than in many other jurisdictions, with distinct thresholds, rates, and rules, especially for non-citizens. Proactive review of estate plans, trust documents, and beneficiaries and restructuring can help preserve wealth and minimize tax.

Special considerations for families

Tax residency often pulls spouses and dependents of global executives into the U.S. tax net as well. Family income, foreign trusts, education costs, and real estate all need to be reassessed under U.S. rules. International families should keep in mind gift tax exposure and reporting obligations for assets held by children, too.

Tax planning strategies

Given the complexity of international relocation, proactive tax planning is vital:

  • Review and restructure foreign investments and trusts prior to moving or receiving a green card.
  • Consider timing of income realization, especially for equity compensation and deferred pay.
  • Seek professional advice on treaty benefits to avoid double taxation.
  • File all required U.S. and foreign tax returns and disclosures.
  • Address estate and gift tax exposures early, especially for large estates.
  • Coordinate with advisors in both home and host countries for holistic planning.

Common pitfalls and risks

Executives often underestimate the requirements of U.S. tax rules. Common mistakes include:

  • Failure to report foreign financial accounts and investments, leading to severe penalties.
  • Inadvertently triggering double taxation by not leveraging treaty benefits.
  • Misunderstanding treatment of equity compensation upon relocation.
  • Neglecting state and local tax exposures.
  • Overlooking estate and gift tax consequences for family wealth.

Conclusion

Relocation to the United States can be a pivotal step in an executive’s career, but it brings a complex and far-reaching tax landscape to navigate. A clear understanding of residency rules, reporting obligations, and the interaction between U.S. and foreign tax systems is essential.

With early planning and the right advisory support, executives can mitigate risk, optimize outcomes, and transition with confidence, protecting both personal wealth and broader organizational interests.
ttg Talent Solution is looking for a Business Developer & Recruiter (Bilingual – English/Spanish) – High commission earnings

Business Developer & Recruiter (Bilingual – English/Spanish) – High commission earnings

Location: Onsite – Coral Gables, FL

Job Type: Full-Time | In-Office | Direct Hire

Schedule: Monday to Friday – 8am to 5pm.

ttg Talent Solutions is seeking a dynamic, self-motivated Double Desk Business Developer & Recruiter to join our Coral Gables team. This role is perfect for someone who thrives in a fast-paced environment, excels in both sales and recruiting, and finds deep satisfaction in earning commissions rather than relying on a base salary.

We are looking for a true hunter who is energized by building new relationships, thrives under pressure, and is passionate about connecting people with opportunities. While a background in staffing and recruitment is a plus, it’s not a must—what we value most is drive, tenacity, and a genuine interest in making a difference one person at a time.

Responsibilities:

  • Identify and pursue new business opportunities within our target markets.
  • Develop and maintain strong client relationships with decision-makers and HR professionals.
  • Promote ttg’s recruitment services and proprietary platform, ttg OPT, as a strategic solution.
  • Negotiate client agreements, pricing models, and service terms in line with ttg standards.
  • Manage the end-to-end recruitment process from sourcing to placement.
  • Leverage ttg’s tools and technology to source, evaluate, and present qualified candidates.
  • Conduct detailed interviews and assess candidates fit both culturally and professionally.
  • Provide white-glove service to candidates, offering regular updates and professional guidance.

Qualifications

  • 3+ years of Staffing and Recruiting experience
  • 3+ years of work experience with Business Development Strategy
  • Proven sales and/or recruiting experience; a dual-track record is highly desirable.
  • Passion for commission-based earnings; self-driven to meet and exceed targets.
  • Strong communication and negotiation skills.
  • Fully bilingual in English and Spanish, highly preferred.
  • Familiarity with the staffing and recruiting industry is a strong advantage but not required.
  • Excellent organizational and time management skills.

What We Offer

·       A supportive and energetic team culture rooted in innovation, empathy, and excellence.

·       The opportunity to grow within a company designed for scalability and national impact.

·       Access to ttg’s proprietary tech platform and marketing tools.

·       A flexible, forward-thinking work environment.

Join us and help redefine what it means to recruit with purpose and passion.

ttg Talent Solutions is an Equal Opportunity Employer and recruiting agency. We are committed to creating an inclusive and diverse work environment and welcome applications from all qualified candidates regardless of race, color, religion, gender, sexual orientation, national origin, age, disability, or veteran status. Please note that all offers of employment are contingent upon the successful completion of a drug test and background check. We maintain a drug- and substance-free workplace to ensure the safety and well-being of all employees.

At ttg, “We believe in making a difference One Person at a Time,” ttg OPT.

Qualified candidates and interested partners are encouraged to connect with us.

Contact:  cmaya@usattg.com | www.usattg.com

How Businesses Are Rethinking Video Content to Scale More Efficiently

By Schnee Vice Productions

Video has become one of the most effective tools for building brand visibility, educating customers, and communicating internally. Yet for many businesses, producing video consistently—especially for social media, marketing updates, and training—requires a significant investment of time, coordination, and budget that is difficult to sustain long term.

At Schnee Vice Productions, we have spent years producing event coverage, promotional videos, and branded content for companies that need to communicate professionally and efficiently. A common challenge we see across industries is not the lack of expertise or ideas, but the ongoing effort required to turn that knowledge into consistent, high-quality video output.

In response to this need, we are launching a new AI-powered video avatar solution designed to help businesses scale their video communication while dramatically reducing time commitment and production costs.

The process is intentionally simple: companies begin with a short, guided recording session to capture a high-quality visual and voice reference. From that single session, AI technology allows us to generate hyper-realistic video content that can be reused and adapted for social media, marketing communication, internal training, and product education—without the need for continuous filming or complex production logistics.

The benefits are practical and measurable:less time spent on content creation, faster turnaround, predictable output, and the ability to maintain a consistent professional presence across multiple platforms. For busy executives and teams, this removes one of the biggest barriers to maintaining consistent visibility in today’s digital landscape.

We are excited to introduce this new capability to IACCSE members and are offering priority access and preferred introductory terms for a limited number of companies interested in exploring this AI-assisted approach.

For more information or to learn more about the IACCSE member pilot opportunity:

Christian Schneeweihs

CEO, Schnee Vice Productions

📞 305-972-8291

📧 christian@schneevice.com

🌐 www.schneevice.com

26th Annual FCBF Golf Classic

By A Customs Brokerage

On behalf of the Florida Customs Brokers and Forwarders Association (FCBF) and FORWARD – Young Professionals in Logistics, we are pleased to invite you to participate as a sponsor in the 26th Annual FCBF Golf Classic, taking place on Friday, June 5, 2026, at Trump National Doral – Red Tiger Course.

With just over two months remaining, we are now entering the final phase of sponsor confirmations. This inaugural event has already generated strong interest across our industry, and several organizations have moved quickly to secure their participation.

As a result, a limited number of key sponsorship opportunities remain, including select premium placements that offer the highest level of visibility and engagement.

This event is more than a tournament; it is a unique opportunity to:

·        Position your organization alongside leaders across the trade and logistics community

·        Engage directly with both established executives and the next generation of industry professionals through FORWARD

We have included the sponsorship package for your review https://www.iaccse.com/wp-content/uploads/2026/03/FCBF-GOLF-26-Sponorships-1.pdf . If you are considering participation, we encourage you to confirm soon to secure your preferred level and ensure full inclusion in event branding and communications.

For questions or to reserve your sponsorship, please feel free to contact me directly or reach out to Gabriel Rodriguez gabriel@acb-us.com or give me a call 305-215-5858.

We appreciate your continued partnership and look forward to having your organization represented in this annual event.

General registration will open in the next two weeks, secure your spot now with a sponsorship! 

SIMEST’s New USA Measure: a strategic tool for Italian companies expanding to the U.S.

By Avv. Stefano Rossi – Partner EXP Legal

Italy has recently strengthened its support for internationalization with the launch of SIMEST’s new “USA Measure”: a dedicated financial package aimed at fostering Italian companies’ presence in the United States. 

The initiative combines subsidised financing and equity instruments, offering an integrated approach to support both market entry and long-term consolidation. It is worth noting that this is not a standalone SIMEST product, but rather a package of additional incentives to be combined with existing SIMEST internationalisation financing tools

With an overall allocation exceeding €300 million, the measure reflects a broader export strategy promoted by the Italian Ministry of Foreign Affairs.

A key feature is the availability of soft loans at highly favorable rates, coupled with non-repayable grants of up to 10% of the financed amount. Additional advantages include 50% advances through an increased first disbursement tranche, as well as financing durations extendable up to 8 years for the “Digital or Ecological Transition” and “Entry into Foreign Markets” products.

In addition, SIMEST can directly support Italian companies through equity investments in U.S. subsidiaries, facilitating the establishment of local entities or joint ventures with American partners. 

Eligible projects include a wide range of activities: setting up commercial networks, strengthening capitalization of U.S. subsidiaries, conducting market analysis, and developing partnerships. The measure is also accessible to companies that are not yet exporters but are part of internationally oriented supply chains. 

Overall, the SIMEST USA Measure offers a concrete opportunity for Italian companies entering the U.S. market. In this context, we remain available, together with the IACCSE, to help companies assess project feasibility, eligibility requirements, and the most appropriate structuring of their investment path.

Refunds of “Global Tariffs”

Following the Supreme Court’s ruling that invalidated IEEPA-based tariffs, all importers of record who paid these duties are entitled to refunds. U.S. Customs and Border Protection (CBP) is processing refunds, including for entries already liquidated, by recalculating duties without the IEEPA charges. Importers should monitor their Automated Commercial Environment (ACE) accounts for refunds, which include interest. CBP had collected approximately $166 billion in duties and deposits associated with these IEEPA tariffs and thousands of importers have brought claims seeking recovery of the amounts paid.

Key Details on IEEPA Tariff Refunds:

  • Eligibility: All importers of record who paid IEEPA-authorized tariffs (e.g., Section 301 tariffs) are eligible for refunds, not just those who filed lawsuits.
  • Process: CBP is directed to liquidate or reliquidate entries “without regard” to IEEPA tariffs. The process involves filing declarations in the Automated Commercial Environment (ACE) system.
  •  Scope: The refund covers over 53 million entries, including over 60% that were informal, indicating a broad application.
  • Action Required: While some refunds may be automatic, experts advise importers to review their entry records, identify IEEPA-paid entries, and ensure protests are filed within 180 days of liquidation if not already covered. an automatic refund system is not yet fully in place, and the process may move forward with some complications.
  • Downstream Customers: Companies that passed these tariff costs to customers may face litigation from those customers seeking to recover their share of the refund. 

Important Considerations:

  • Timing: While the Court of International Trade (CIT) has ordered refunds, the process may still take time to fully execute.
  • Interest: Refunds will include interest, which must be accounted for in financial and tax filings.
  • Documentation: Accurate documentation of the paid IEEPA duties is crucial for securing the full refund amount. Gather the relevant documentation, including Entry Summaries (CBP Form 7501), proof of payment, and the tariff classifications applied.

For the most up-to-date information, consulting with legal counsel specializing in international trade is recommended. 

Uneven Performance of Italian Exports To The United States in 2025 

The first data published on Italian exports to the United States during 2025 point to a highly uneven situation across sectors, partly due to the impact of tariffs introduced by the U.S. federal government on foreign products.

According to an analysis by Italian Institute of Statistics, ISTAT , the aggregate figures show an overall 7.2% increase in Italian exports to the United States in 2025, which remain the second most important market for Italy, after Germany. However, this positive figure masks a more complex reality. The growth has been driven almost entirely by the sharp increase in pharmaceutical exports, which surged by 54%, reaching €15.7 billion and accounting for 22.7% of Italy’s total exports to the U.S.

When this pharmaceutical effect is excluded, the picture changes significantly. Italian exports would show an overall decline of 1.7%, equivalent to about €863 million less

Among the sectors most affected are several pillars of Italian manufacturing. The automotive sector declined by 18.5%(–€655 million), agri-food exports fell by 4.5% (–€348 million), wood and furniture dropped by 8.2%, and machinery declined by 3.4%. By contrast, the fashion sector—including textiles, clothing, and leather goods—proved more resilient, posting a 2.4% increase and reaching €5.7 billion.

In 2025, there were also significant increases in exports of ships to the United States (+111%) and aircraft and related components (+290%), sectors characterized by high value-added products and longer production cycles.

Aggregate data from the United States Census Bureau, however, show a different figures and  somewhat different  picture. In 2025, U.S. exports to Italy rose to $43.7 billion (up from $32.4 billion in 2024), while U.S. imports from Italy declined slightly to $74.4 billion, compared to $76.3 billion the previous year. As a result, the trade surplus in Italy’s favor, while still substantial, narrowed from $44.0 billion in 2024 to $30.8 billion in 2025. These figures refer exclusively to trade in goods and are expressed in nominal U.S. dollars.

Accessibility Toolbar